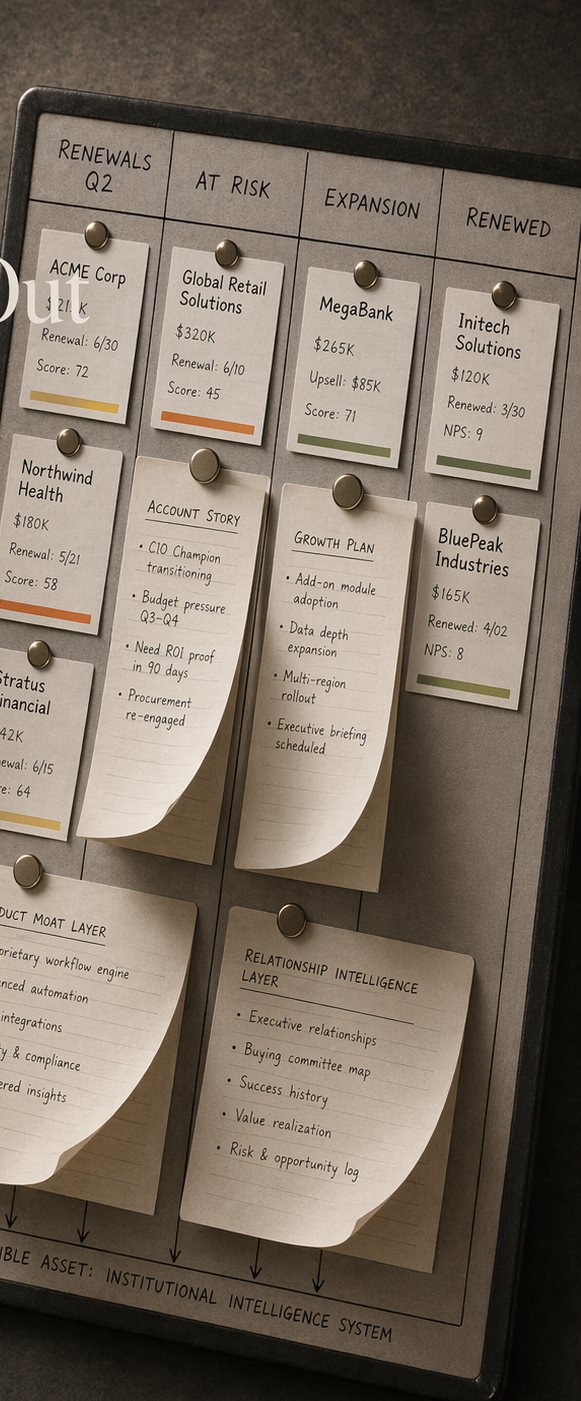
What's Changing Inside Your Post-Sale Engine
Your cost-to-serve is climbing. Your senior CSMs are eighteen months from their next job. Your founding engineers are in the same market. Your twelve-month implementations have not compressed in half a decade. A briefing for operations leaders at mid-market enterprise SaaS firms.
You have seen this on your post-sale floor
Every Chief Operating Officer or Chief Customer Officer at a mid-market enterprise SaaS firm in Europe has had the same Monday morning. Three post-sale reviews on this week's calendar. Implementation one: a mid-market rollout at a regulated customer, go-live slipped twice because the integration is more complex than the playbook modelled, and your lead solution architect has rescheduled hypercare for the third time. Expansion two: a seven-figure add-on, the customer asked for a reference architecture on Friday's call that nobody on your side could produce without pulling three solution architects into a Slack huddle. Renewal one: your ten-year senior CSM resigned Friday. She carried six accounts up for Q3 renewal. You know the status of two. And then there is the calendar block you noticed on your VP of Engineering's diary this morning, with a recruiter's name on it.
You have run this function for four years. The pattern used to be simple. Hire good CSMs. Hire senior solution architects. Build playbooks. Hold gross retention. Keep NRR moving. The business was understandable.
Something changed. Your support queue is at four-hundred tickets against a normal two-forty because the product team shipped an AI feature two weeks ago and support never got a runbook. Your implementation backlog has customers in queue who will not see hypercare until next quarter. Your NRR came in at one-oh-one percent, four points below plan. And you can name the senior CSMs whose next resignation email will take ten years of customer context out the door with it. You can also name the three founding engineers whose next offer will take the architectural reasoning with them.
This is not a you problem. It is an industry problem and a post-sale problem and a product-knowledge problem, happening at the same time. Most enterprise SaaS COOs are treating them as three. The ones who see them as one are going to own the next decade.
This briefing covers what is happening in your sector, what it means inside your delivery engine, and the three questions your operations team should answer before the next board cycle.
Mid-market enterprise SaaS just lost the moat that ran it for a decade
Every technology wave your sector absorbed in the last fifteen years added to the product. Workflow specificity deepened. Integration libraries widened. Data schemas grew. Feature parity was the moat, because building complex platform features took years and serious capital. A well-funded competitor needed three years and fifty engineers to close the gap on a mid-market incumbent. Your rate of feature release kept you ahead. Your customers renewed because the integration was painful to unwind.
AI does not behave the same way. A well-funded entrant with ten engineers and foundation models reaches feature parity in twelve to eighteen months on categories that took your firm five years to build. The product floor is collapsing. What your customers have been renewing for, the accumulated understanding of their workflows that lives inside your CSMs' heads AND the architectural reasoning behind your data model that lives inside three founding engineers' heads, is still defensible. But your firm has never captured either. Under renewal pressure from an AI-native entrant asking questions your team has never asked, and under recruiter pressure on the exact people who carry the architectural reasoning, your incumbent advantage depends on infrastructure you have not built.
Procurement teams are arriving at renewals with comparison quotes that show your ACV against an AI-native alternative at sixty percent of your price. At the same time, recruiters are arriving at your founding engineers with offers your firm has never seen.
The competitors in your segment are not waiting. A handful of Nordic and continental enterprise SaaS firms have committed serious budget to institutional intelligence infrastructure in the last eighteen months, covering both the customer side and the product-knowledge side. The ones moving first are closing implementations in four to six weeks that used to take fourteen, at the same ACV, with hypercare completing inside the same quarter as kickoff. They are also holding their senior bench through a recruiting market that has drained their competitors. The other half of the story sits on the segment side. Customers below your current implementation-cost floor, the long tail you walked away from because fixed implementation cost was too heavy, are suddenly addressable.
Your post-sale engine is feeling it every day
Your implementation engine. Lead solution architects are working harder to close kickoffs at the same quality. Handoffs between sales, scoping, and delivery carry friction built into a 2018 on-prem-era workflow and never redesigned. The firm runs a complex implementation the same way it did in 2020. The tooling has changed, the customers have changed, expected time-to-first-value has changed. The engine has not.
Your customer success function. The health score still shows green. But the score is backward-looking, and the renewal lands when the CSM's judgment hits the QBR, not when the dashboard changes colour. Your senior CSMs are the people who read the warning signal two quarters before the data shows it. That judgment has never been written down. When your ten-year senior resigns, the firm sees the next renewal before the dashboard does, and the account goes to competitive review the quarter after the announcement.
Your support and technical operations. Tickets are climbing faster than ARR. Tier-one volume doubles every time the product team ships a new AI feature without a runbook. Cost per ARR dollar on support has drifted upward every quarter for two years. Customer expectations on response time reset every year and your support model has no more capacity to give. Most of your tier-one resolution work now compresses to seconds with the right infrastructure. Your support team has not had the conversation yet about what tier-one becomes.
Your senior bench AND your product edge. Your four to ten most senior CSMs carry twelve to thirty accounts each. Every one is twelve to eighteen months from their next role in a market where AI-native competitors are actively recruiting. Meanwhile your three to five founding engineers and senior solution architects carry the architectural reasoning behind every integration you have built. Every one of them is in the same recruiting market. The scarcest resource in the firm sits in two places at once, and neither one is written down.
Your customer AND product continuity. Your top accounts each carry between two and four relationships worth €500K to €3M in annual ARR and services. The senior CSMs who built those relationships spent four to ten years learning each customer's political structure. The solution architects and founding engineers who built the integrations spent as long learning each customer's data quirks and regulatory surface. When one senior leaves, industry experience is that one of those accounts goes to competitive review within twelve months. You know which resignations are coming.
The firms pulling ahead are building one piece of infrastructure
Your sector is compressing from below because AI takes hours out of implementation and tier-one support. Your post-sale engine is compressing from above because your senior CSMs and solution architects are spending half their week on the routine coordination work the firm has not built infrastructure to carry. Same force, two altitudes. But there is a third thing happening most enterprise SaaS COOs have not named yet, and it is the one that matters most.
Your CEO, your CPO, and your senior CSMs are all trying to build the same asset. None of them know it. The customer intelligence your CEO is trying to build at the firm level is the same intelligence your senior CSM is trying to hold in her head, AND it is the same shape as the architectural reasoning your founding engineer carries in his. Your function sits at the intersection no other exec can see fully. Every margin drift, every retention risk, every slow implementation, every quarter of product responsiveness erosion after a founding-engineer resignation is a symptom of that single unsolved thing.
Look at the firms pulling ahead. Implementation, CS, support, and the architectural edge of the product are not four separate programmes. They are one piece of institutional intelligence infrastructure. Every implementation feeds it. Every renewal tests it. Every CSM who leaves adds customer context to it on the way out. Every engineer who leaves adds architectural reasoning to it. The same infrastructure that protects gross retention shortens time-to-value, brings cost-to-serve down, and holds your competitive response capability against AI-native entrants.
You can tell which camp a firm is in from one question. Name one thing about your top ten customers, AND one architectural decision about your product, that you understand better this quarter than last. Most enterprise SaaS operators cannot answer either half.
You have eighteen to twenty-four months. The AI adoption debate is over. Your question now is whether you build the institutional intelligence your firm will run on for the next decade, or wait until the CFO brings in a vendor to build one that belongs to someone else.
What most firms are doing. What the winners are doing instead.
Every enterprise SaaS COO has had the AI conversation. Most are making the same four decisions. A smaller group is making different ones. The difference is architecture, not tooling.
| The default path | The winners' path |
|---|---|
| Hold ACV, push CSM and architect load upSame pricing, harder targets. NRR drifts as AI-native entrants arrive with comparison quotes at sixty percent. | Rebuild around dual intelligence as the moatCustomer knowledge AND architectural reasoning become institutional. NRR holds because switching is painful in a new way. |
| Treat CSM and engineer turnover as HR problemsBackfill fast, hope notes are in the CRM and Confluence, watch renewals and roadmap velocity slip after each departure. | Extract judgment as a side-effect of daily workCapture from QBR decks, renewal memos, design docs, engineering tickets. People become the strategic escalation layer. Knowledge stops walking out. |
| Deploy copilots on top of the existing engineEvery CSM and engineer gets a chatbot. Productivity rises individually. Time-to-value does not move because the engine is still 2018. | Rebuild the engine around the new unitJunior CSM plus agent plus extracted customer context, junior engineer plus agent plus extracted architecture, delivers senior-tier output. |
| Defend mid-tier roles by avoiding the conversationPretend roles do not change. Lose the best to firms that moved first. Bench thins at the worst moment. | Redesign the junior pathway around judgmentNew hires pair with agents and the firm's institutional intelligence. Five-year curve compresses to eighteen months. |
Same post-sale engine. Same twelve months. Opposite outcomes. The difference is the architecture, not the agents.
Unit Economics. Customer Outcomes. Time-to-Value.
Three questions every enterprise SaaS COO is tracking. None of them used to be the same question. They are now.
Why is our cost-to-serve rising faster than our ARR per customer?
The ACV has not moved. Headcount is within plan. But cost per ARR dollar on CS, implementation, and support is up quarter over quarter, and AI-native entrants are quoting the same customer at a materially lower implementation cost. Every implementation re-learns what the last already knew. Support cost climbs because customer expectations reset every year. The pricing is fine. The delivery architecture is the question.
What happens to our NRR when our senior CSMs AND our founding engineers resign?
Your senior CSMs are within eighteen months of their next role. Your founding engineers are in the same recruiting market. Each one carries knowledge that took years to build and has never been written down. Gross retention holds because the CSMs are in the renewal call. Competitive response holds because the engineers are in the architecture review. When either layer leaves, the consequences show up in different quarters but from the same mechanism.
Why has our implementation cycle not moved in five years?
A complex enterprise implementation takes ten to sixteen weeks on a standard mid-market rollout. Roughly half is requirements gathering, configuration mapping, data migration, and standard integration work that now compresses to hours not weeks. The firms that rebuild delivery around this close the same implementation in four to eight. Same ACV. Same quality. Eight to ten weeks of ARR pulled forward per customer. Not a productivity story. A capacity story.
What the firms winning this play are actually doing
Four moves any enterprise SaaS COO can start this quarter. Each touches one part of the post-sale engine. Pulled together, they become one architecture.
Implementation: decompose every template to the task level, then build configuration and integration agents around the tasks that still make money
Most COOs are redesigning implementations. The right unit is the deliverable task. List the task bundles inside each implementation type. Mark each: agent-owned with human audit, hybrid, senior-only, retired. What remains is a different implementation at a different cost base and timeline. The COO who walks into the next pricing review with the task-level map owns the conversation.
Customer success AND architecture: extract judgment now, as a side-effect of daily work, not as a separate knowledge project
Documentation sprints have failed in every software firm for fifteen years. Judgment is not articulable in prose. Extract from the artefacts the CSM already produces: QBR decks, renewal memos, escalation notes, Slack threads. And from the artefacts your engineers produce: design docs, architecture decision records, engineering tickets. Both layers become the strategic escalation layer for their domain.
Bench: redesign the junior CSM AND junior engineer pathways around judgment from day one
The tier-one coordination work and the routine engineering work that trained juniors into seniors is now running on agents. No routine work, no training ground, no senior bench in 2031. New hires start on renewal risk analysis, executive escalation, architectural reviews, and paired work with seniors on live accounts and complex integrations. The five-year curve compresses to eighteen months on both tracks.
Continuity: institutionalise both the customer relationship AND the product reasoning, so both transfer on architecture
Every enterprise SaaS CEO has lost a seven-figure account once, the quarter after the CSM who held it resigned. Most have also watched roadmap velocity stall for two quarters after a founding engineer left. Treat every major account as a customer-intelligence asset, and every major product decision as an architectural-reasoning asset. When anyone rotates, the next senior inherits the asset.
The only firm joining post-sale advisory to working infrastructure
The enterprise SaaS COO has four places to go for help. None can do what we do.
The big consultancies' enterprise-SaaS practices sell €500K to €2M diagnostics delivered by partners and analysts billing hours. They produce decks. They cannot put working infrastructure into a CSM's and an engineer's Monday workflow in three months. Their revenue model is the thing being disrupted.
The customer-success and customer-data platforms sell dashboards on top of your existing intelligence problem. They treat health scores as the answer. Judgment extraction is not on their roadmap. Product-side reasoning is not in scope at all.
The hyperscaler professional services arms sell migrations tuned to their cloud platform. They build agent modules on their stack. Your customer intelligence and architectural reasoning get absorbed into the platform. The eighteen-month moat becomes a platform asset.
The AI point-vendors for CS, implementation, and developer productivity sell per-seat agent licences that draft QBR memos or generate code. They automate the output without capturing the reasoning. The memo is faster. The judgment still walks out with the CSM, and the architectural reasoning still walks out with the engineer.
The market offers four things you have already said no to. GRAIL is the fifth option.
- Senior advisory that speaks post-sale-floor, not diagnostic-deck
- Working infrastructure your CSMs and architects use the same week
- Custom agents built on your accounts, your product, your domain
- A dual intelligence asset your best people feed
- No vendor lock-in at any phase of the engagement
- Founded by operators who have run SaaS post-sale and product
- Business first, technology second
- Three weeks from first meeting to working infrastructure
- Your teams keep the infrastructure, you own the IP
- Every next step earned by what just shipped, never assumed
Three sessions with your post-sale leadership. Working infrastructure from week one.
We start with your post-sale leadership because the change cannot outrun the team's personal understanding of what is possible. Three workshops. Each delivers standalone value. Each earns the right to the next.
How to think
Walk through what is happening in your sector and inside your post-sale engine. Build the first piece of infrastructure in the room: a customer-specific agent for one of your real seven-figure accounts, extracted from the QBR decks and renewal memos you already have. Your operations team leaves with a shared view and the first piece of working infrastructure already in their hands.
Your institutional intelligence
A half-day build. Your Head of CS, Head of Implementation, Head of Support, and (where relevant) your VP of Engineering or senior solution architect each leave with five to ten pieces of working infrastructure tuned to their function. QBR preparation. Renewal memo drafting. Integration-pattern agents. Architectural decision capture. Infrastructure your teams are using the same week.
Ready to run
Refined infrastructure based on real use. The rollout plan to your wider post-sale and engineering organisations. The knowledge-extraction plan for your senior CSMs and your founding engineers. The pathway plan for your junior CSMs and junior engineers. And the CEO and CFO conversation with numbers they can check.
Three weeks. No IT project. No board approval needed to start. The infrastructure your post-sale engine is already running on when we finish.
For your next operations review
The questions where your operations team cannot agree on an answer are the ones worth an hour on the agenda. Ask these honestly.
Of the last ten renewals where NRR came in under plan, how many lost ground because an AI-native entrant arrived with a comparison quote your team had not seen? If you do not know, how would you find out?
What percentage of your senior CSMs' AND senior architects' week is spent on QBR prep, renewal memo drafting, configuration mapping, and integration coordination? What would it take to cut that in half?
If your top three senior CSMs and two founding engineers resigned next year, what would happen to the accounts and the roadmap? What have you actually transferred to the rest of the bench in the last twelve months?
Can you name one thing about your top ten customers AND one architectural decision about your product that you understand better this quarter than last? If not, what are the next four quarters going to add up to?
Which of your junior CSMs and junior engineers is already working the way the rest of the bench will need to work by 2027? What would it take for that to be the default across your post-sale and engineering organisations?
If any of these produces a disagreement in your operations team, that is the conversation worth having before the board asks.
Continue reading
Sources and limitations
This briefing draws on GRAIL's engagement experience with leadership teams and on public company disclosures. Figures are illustrative unless a source is named beside them. A sourced edition is in preparation.