What's Changing in How You Bind Risk
Your loss ratio is creeping on classes the rating plan says should hold. Your senior underwriters are five years from retirement. Your quote cycle has not moved in a decade. Three problems that look separate, but are actually one. A briefing for underwriting leaders at mid-market specialty insurers.
You have seen this on your underwriting desk
Every Chief Underwriting Officer or Head of Underwriting at a mid-market specialty carrier in Europe has had the same Monday morning. Three submissions on the desk. Submission one: a marine hull risk, the twenty-eight year class lead is the only one who can smell the dodgy survey report, and he has been at a broker in Rotterdam. Submission two: a mid-market cyber risk, the mid-tier underwriter spent four hours rekeying the SIG and running aggregations a platform the firm already licenses could have done in six minutes. Submission three: a fifteen-year renewal. The senior who has carried it since 2011 scheduled thirty minutes with you for Thursday. The subject line says retirement.
You have run this book for fifteen years. The pattern used to be simple. Hire the best underwriters you could find. Let them build their brokers. Protect the combined ratio. Hold rate through the softening cycle. The business was understandable.
Something changed. Your loss ratio on two core classes is creeping up despite the same rating plan, and AI-native carriers are quoting against your book with a different cost base. Your senior underwriters are the scarcest resource in the firm, and they are spending half their week on triage and aggregation the firm has not built infrastructure to carry. Your quote cycle has not meaningfully shortened in a decade despite the tooling that exists now. And you can name the six underwriters whose retirement inside five years will cost you more than any expense ratio programme has ever gained you.
This is not a you problem. It is an industry problem and an underwriting operation problem, happening at the same time. Most carrier CUOs are treating them as two. The ones who see them as one are going to own the next decade of mid-market European specialty insurance.
This briefing covers what is happening in your sector, what it means inside your underwriting operation, and the three questions your underwriting committee should answer before the next capacity review.
Specialty insurance just lost the pricing shelter it had for a generation
Every technology wave your sector absorbed in the last thirty years gave carriers a reason to hold rate. Pricing models got more sophisticated. Aggregation tools got better. Regulatory filings got heavier and pulled more specialists into every class. Each new layer justified the expense ratio that paid for the bench. The business ran on rate integrity, broker relationships, and class specialisation, and for a generation, the mid-market carrier could defend a combined ratio that the largest players struggled to reach.
AI does not behave the same way. The broker still brings the same submission, the same loss history, the same client need. The risk is unchanged. But the routine triage layer that used to absorb most mid-tier underwriter hours can now be done in seconds by platforms your competitors have already stood up. Under the current quote mechanic, that faster quote at the same rate means your carrier arrives at the market third, on a shrinking book of what the broker still brings to the traditional desk. Your sector calls this the AI-native repricing, and for the first time in a generation, the rate advantage is actually sliding.
Your brokers are placing against carriers that quoted in twenty minutes what your desk quoted in four days. By the time your underwriter rings the broker back, the risk is bound somewhere else.
The competitors in your segment are not waiting. A handful of Nordic and continental specialty carriers have committed serious capacity to agent-led underwriting infrastructure in the last eighteen months. The ones moving first are quoting standard-risk classes in twenty minutes at the same rate card, with loss ratios running three to six points inside peers. The other half of the story sits on the broker side. Mid-market SME classes that required fifteen-thousand-euro minimum-viable-quote economics are suddenly the addressable segment, because the same underwriting judgment now delivers at entry points near three thousand. The carrier that opens that segment first captures a decade of broker trust the incumbents never priced for.
Your underwriting engine, your bench, and your claims operation are feeling it every day
Your underwriting engine. Your underwriters are working harder to move submissions through the same quote cycle. Handoffs between triage, rating, referral, and binding carry friction that was built when the desk was organised around a 2008 workflow and never redesigned. The firm quotes property the same way it quoted property in 2015. The tooling has changed, the brokers have changed, the regulatory surface has changed. The underwriting engine has not.
Your portfolio quality. The combined ratio floor still holds. The rate-adequacy ceiling has not risen in ten years. Both of those are now at risk. The senior underwriters who catch the risk a junior would miss, who read the loss triangle before it appears in the reserving report, who walk a reinsurer through an unwritten placement quirk, carry that judgment as biography. It has never been written down. When one of them retires, the book runs two renewals with a visible rate-integrity gap before the reinsurer notices. Three renewals before pricing terms move. Five before the treaty goes to co-lead.
Your specialist bench. Your mid-tier underwriters spend four to six hours a week on submission triage, data rekeying, sanctions checks, and aggregation runs that AI platforms now do in seconds. The expense ratio still reads the same number. Realisation against the time the firm is paying for is drifting quarter on quarter on every book where a competitor has stood up the infrastructure. Utilisation of what your bench is actually paid to do, which is underwrite, is harder to defend every quarter. Most of your mid-tier bench has not had a conversation yet about what the next version of their role looks like.
Your senior underwriters. Your twenty to forty most senior class leads cost the firm between two hundred eighty and four hundred twenty thousand euros fully loaded. On a standard week they deliver twelve to eighteen hours of the complex binding work only they can carry. The remaining twenty-two to twenty-eight hours go into triage review, aggregation sign-off, sanction clearance, regulatory filings, reinsurer correspondence, and internal coordination. Substrate work the firm has not yet built infrastructure to hold. The scarcest resource in the firm is spending half its week on the work it is least suited for.
Your claims operation. Your top three senior claims leads each carry between forty and one hundred twenty million euros of reserve judgment across long-tail books. They built that judgment on twenty to thirty years of litigation history, broker-counsel relationships, settlement patterns, and class-specific loss behaviour, never written down. When one of them retires, industry experience is that reserving consistency moves two to four points in the first year, and the firm finds out twelve months later when the reserve development triangle reprints. The retirement conversations are already on your calendar. You know which ones.
The carriers pulling ahead are building one piece of infrastructure
Your sector is compressing from below because AI takes hours out of mid-tier triage. Your underwriting engine is compressing from above because your senior underwriters are spending half their billable week on substrate work the firm has not built infrastructure to hold. Same force, two altitudes. But there is a third thing happening that most carrier CUOs have not named yet, and it is the one that matters most.
You do not have three problems. You have one. The senior judgment that makes your combined ratio has never been separated from the underwriter who carries it. Every loss-ratio drift, every retention risk, every stuck quote cycle is a symptom of that single unsolved thing. Pay a senior underwriter to do triage a platform can do, and your cost of underwriting a binder drifts. Let a senior retire with their class-specific loss judgment still in their head, and the treaty goes to co-lead. Keep the underwriting engine designed around a bottleneck that cannot be unblocked, and the quote cycle cannot shorten.
Look at the carriers pulling ahead. Underwriting, bench, and claims continuity are not three separate programmes. They are one piece of infrastructure. Every submission makes the infrastructure smarter. The senior who retires adds to it on the way out. The mid-tier learns by using it. The claims case that settles feeds the next quote. The same infrastructure that protects combined ratio protects treaty continuity and shortens quote cycle.
You can tell which camp a carrier is in from a single question. Can you point to one thing in your book that is measurably smarter this quarter than last quarter? Most carriers cannot. The ones that can have already made the shift, and they are already quoting the risks you thought were yours.
You have eighteen to twenty-four months. The AI adoption debate is over. Your question now is whether you build the infrastructure your carrier will run on for the next decade, or wait until the CFO brings in a vendor who will build one that belongs to someone else.
What most carriers are doing. What the winners are doing instead.
Every carrier CUO has had the AI conversation. Most are making the same four decisions. A smaller group is making different ones. The difference is architecture, not tooling.
| The default path | The winners' path |
|---|---|
| Hold the rate plan, push underwriter volume upSame quote mechanic, harder targets. Loss ratio drifts as AI-native carriers arrive with faster quotes on the same risks. | Rebuild the desk around substrate plus senior judgmentAgents handle triage, sanctions, aggregations. Seniors bind. Quote times compress and rate integrity holds. |
| Treat senior retirements as an HR problemMentor, hire replacements at premium, and watch a treaty move to co-lead eighteen months after each departure. | Extract senior judgment as a side-effect of daily workCapture from the artefacts they already produce. Seniors stay the escalation layer. The judgment stops walking out. |
| Deploy copilots on top of the existing workflowEvery underwriter gets a chatbot. Productivity rises individually. Quote cycle does not move because the desk is still 2008. | Rebuild the desk around the new unit of bindingJunior plus agent plus extracted judgment delivers senior-tier quotes. Cycle compresses from four days to twenty minutes. |
| Defend the mid-tier by avoiding the conversationPretend roles do not change. Lose the best mid-tier to carriers that moved first. Bench thins at the worst moment. | Redesign the junior pathway around judgment from day oneNew hires pair with agents and the firm's extracted corpus. Five-year curve compresses to eighteen months. |
Same underwriting operation. Same twelve months. Opposite outcomes. The difference is the architecture, not the agents.
Loss Ratio Discipline. Combined Ratio Defence. Quote-to-Bind Speed.
Three questions every carrier CUO is tracking. None of them used to be the same question. They are now.
Why is our loss ratio creeping on classes the rating plan says should hold?
The rating plan has not moved. Aggregates are within appetite. But adverse selection is arriving faster on the risks the broker cannot place at the AI-native carrier first, and the override judgment that used to catch them is thinning every time a senior retires. The loss ratio on two core classes is sliding three to six points against two years ago. The rating plan is fine. The risk-selection discipline behind it is the question.
What happens to our combined ratio when our senior underwriters retire?
Six to fourteen of your most senior class leads are within five years of retirement. Each one carries loss-pattern judgment that took twenty-five years to build and has never been written down. The combined ratio holds because they are in the room. When they leave, the rate integrity slips before the reinsurer notices, and the treaty they held goes to co-lead the quarter after the announcement. You already know which conversations are on your calendar.
Why has our quote cycle not moved in a decade?
A standard quote on a mid-complexity risk takes four to seven days on your desk. Roughly half of that elapsed time is triage, data rekeying, sanctions clearance, and aggregation runs that now compress to seconds. The carriers that rebuild the desk around this quote the same risk in twenty minutes. Same rate integrity. Same capacity discipline. Forty percent more bindings per underwriter. Not a productivity story. A capacity story.
What the carriers winning this play are actually doing
Four concrete moves any carrier CUO can start this quarter. Each touches one part of the underwriting operation. Pulled together, they become one architecture the firm runs on.
Underwriting engine: decompose every class's submission-to-bind flow to the task level, then rebuild authority around the tasks that still make money
Most CUOs are redesigning class workflows. The right unit is the task. List the task bundles inside each class's submission-to-bind flow. Mark each: agent-owned with human audit, composite, senior-only, retired. What remains is a different desk at a different cost base and a different quote speed. The CUO who walks into the next capacity review with the task-level map owns the conversation. The ones with class-level P&Ls are running the 2019 playbook.
Portfolio quality: extract senior underwriter override judgment now, as a side-effect of daily work, not as a separate knowledge project
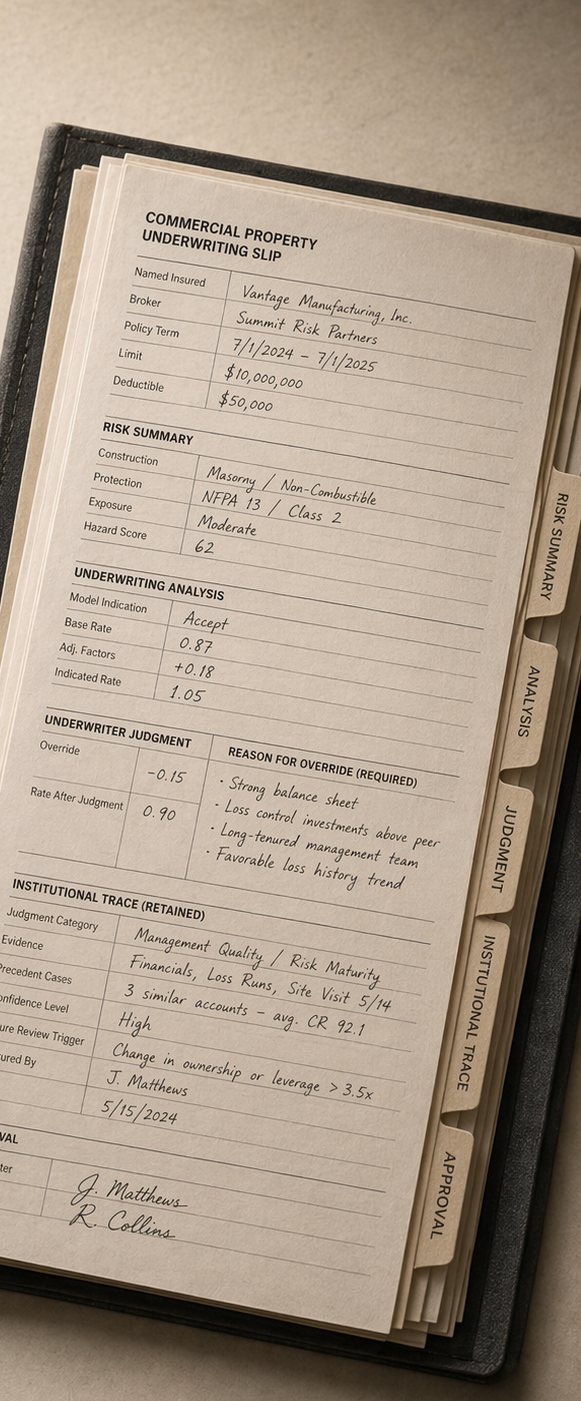
Documentation sprints and mentoring have failed in every carrier for thirty years. The judgment is not articulable in prose. Extract from the artefacts the senior already produces: file notes, referral decisions, redlined slips, post-loss reviews, reinsurer correspondence. The firm captures the override reasoning as a side-effect of paid work. Senior consent is straightforward because they are not asked to explain themselves. Their role elevates from binder to escalation. The judgment stops being biographical.
Specialist bench: redesign the junior pathway around composite work from day one, not routine triage
The routine triage that trained juniors into mid-tier underwriters is now running on agents. No routine work, no training ground, no senior bench in 2031. New underwriters do not start on sanctions and rekeying. They start on referral review, exception handling, and paired work with seniors. The five-year curve compresses to eighteen months. The junior who in 2022 built competence through three years of triage now builds it through three years of judgment at volume.
Claims continuity: institutionalise reserving judgment, so it transfers on architecture, not biography
Every carrier CEO has watched reserve development move two points once, the year after the senior claims lead retired. The move is to treat every long-tail class as a small intelligence asset under active construction. Ten years of claim history. Accumulated judgment from every senior who served it. Counsel relationships, settlement patterns, litigation quirks. When the senior retires, the next claims lead inherits the asset. The reserves hold on the firm's architecture, not the adjuster's biography.
The only firm that speaks your desk and builds what you use
The carrier CUO has four places to go for help. None of them can do what we do.
The big consulting firms' insurance practices will sell a €500K to €2M diagnostic delivered by a partner and analysts billing hours. They produce decks. They cannot put working infrastructure on an underwriter's desk in three months.
The policy-administration and underwriting-workbench vendors will sell an eighteen-month platform implementation with metadata tagging. They treat your senior's judgment as a data field to file. Every carrier has watched that purchase overrun once already.
The AI-native underwriting platform vendors will sell an agent module on their platform with their data contracts. They are the layer repricing your mid-tier. The carrier-specific judgment gets encoded into their system, not yours.
Your internal IT function and the RPA platforms will build a chatbot or an automation pilot. IT optimises for standardisation. It does not sit close enough to how your seniors reason to codify override judgment.
The market offers four things you have already said no to. GRAIL is the fifth option.
- Senior advisory that speaks underwriting-floor, not diagnostic-deck
- Working infrastructure your underwriters use the same week
- Custom agents built on your classes, your brokers, your loss history
- The start of a knowledge infrastructure your best seniors feed
- No vendor lock-in at any phase of the engagement
- Founded by operators who have run senior-judgment functions
- Business first, technology second
- Three weeks from first meeting to working infrastructure
- Your underwriters keep the infrastructure, you own the IP
- Every next step earned by what just shipped, never assumed
Three sessions with your underwriting leadership. Working infrastructure from week one.
We start with your underwriting leadership team because the change cannot outrun the team's personal understanding of what is possible. Three workshops. Each delivers standalone value. Each earns the right to the next.
How to think
Walk through what is happening in your sector and inside your underwriting operation. Build the first piece of infrastructure in the room: a class-specific agent for one of your real books, extracted from the submission archive you already have. Your underwriting leadership leaves with a shared view of what to do next and the first piece of working infrastructure already in their hands.
Your underwriting infrastructure
A half-day build. Your Head of Underwriting, Chief Actuary, Head of Claims, and Head of Bench each leave with five to ten pieces of working infrastructure tuned to their function. Submission triage. Aggregation analysis. Sanctions clearance. Class-specific override judgment capture. Reserve-consistency agents. Infrastructure your teams are using the same week, not decks about infrastructure.
Ready to bind
Refined infrastructure based on real use. The rollout plan to your wider underwriting organisation. The knowledge-extraction plan for your senior class leads. The pathway plan for your mid-tier underwriters. And the CEO and CFO conversation with numbers they can check: gross written premium per underwriter, loss ratio by class, retention exposure by senior.
Three weeks. No IT project. No board approval needed to start. The infrastructure your desk is already running on when we finish.
For your next underwriting committee
The questions where your underwriting committee cannot agree on an answer are the ones worth an hour on the agenda. Ask these honestly.
Of the last ten renewals where loss ratio came in worse than plan, how many lost ground because the broker placed with an AI-native carrier first and we got the adverse selection? If you do not know, how would you find out?
What percentage of your senior underwriters' week is spent on triage, sanctions, aggregation, and regulatory documentation, and what would it take to cut that in half?
If your top three senior class leads retired next year, what would happen to the treaties they carry? What have you actually transferred to the rest of the bench in the last twelve months?
Can you point to one thing in your book that is measurably smarter this quarter than last quarter? If not, what are the next four quarters going to add up to?
Which of your mid-tier underwriters is already working the way the rest of the bench will need to work by 2027? What would it take for that to be the default across your desk?
If any of these produces a disagreement in your underwriting committee, that is the conversation worth having before the board asks.
Continue reading
Sources and limitations
This briefing draws on GRAIL's engagement experience with leadership teams and on public company disclosures. Figures are illustrative unless a source is named beside them. A sourced edition is in preparation.