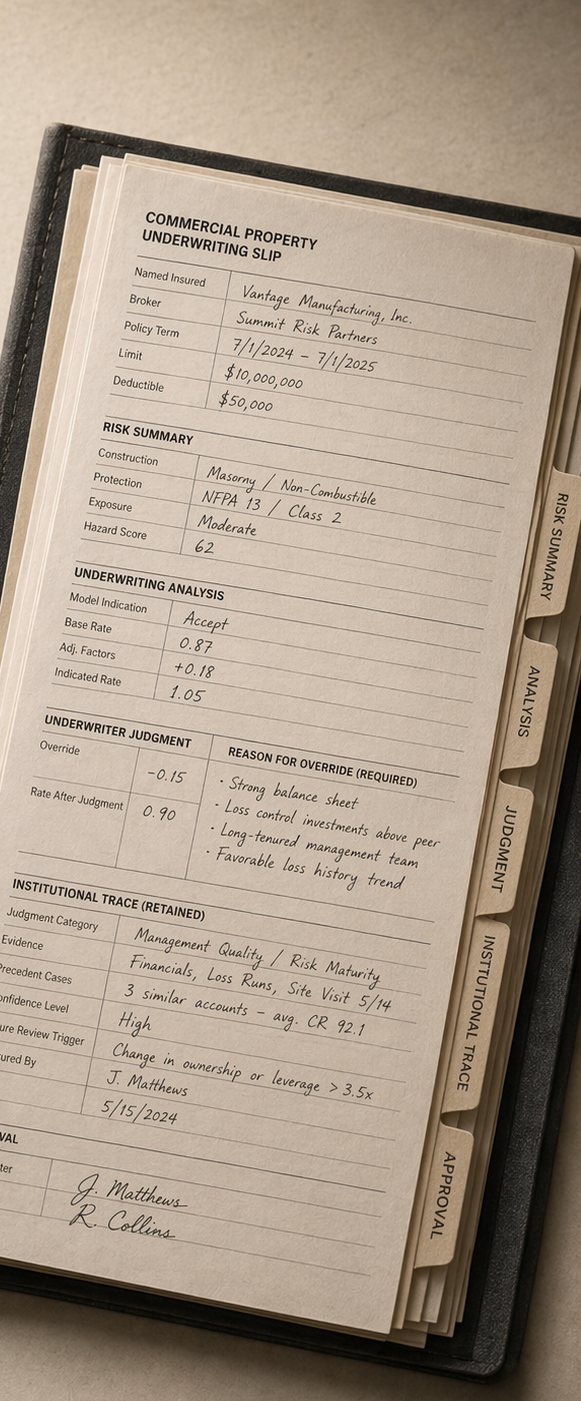
The Judgment Walks Out
Your best underwriters override the pricing model regularly, and they are usually right. The question is what happens to that judgment when they are gone. A briefing for insurance CEOs navigating the gap between algorithmic pricing and human expertise.
What changes for the insurance company as AI enters its industry
Mid-market insurance built its competitive position on two assets: specialist underwriting judgment and long-standing broker relationships. AI is compressing both. Algorithmic pricing models commoditize the quantitative layer of underwriting. AI-native MGAs are binding risk at half the turnaround time with structurally lower cost bases. Broker consolidation is eroding the informal advantages that came from decades of relationship trust. The two pillars that held up the mid-market carrier are under simultaneous pressure.
What remains defensible is the human judgment that overrides the model. Knowing when the data lies. Sensing when a broker is packaging risk creatively. Reading a market turn before the loss data confirms it. That judgment is the remaining competitive asset. It is also entirely tacit, held by senior underwriters who are approaching retirement, and invisible to every system in the organization. When they leave, the quality of risk selection degrades. The combined ratio deteriorates. But the damage does not appear for twelve to eighteen months, until the losses emerge. By then it is too late to reconstruct the judgment.
For the insurance CEO, this is a revenue question, a profit question, and a valuation question. Revenue, because AI-native competitors are winning broker placements on speed and price. Profit, because combined ratio deterioration from lost underwriting judgment is delayed but devastating. Valuation, because the carrier that can demonstrate institutional underwriting discipline earns capacity and reinsurance terms the carrier running on personal expertise cannot.
The strategic move is not to compete on pricing speed against AI-native MGAs. That race favors the entrant. It is to encode the underwriting judgment before the people who carry it retire, build systems that capture and compound override intelligence, and demonstrate to reinsurers and capital providers that the underwriting edge is institutional, not personal. The companies that move first do not just protect what they have. They rebuild the competitive position on foundations that survive a generation of retirements.
This briefing is about what that move looks like, and how a management team gets it done before the next wave of senior underwriter departures.
The underwriting edge is aging out. What replaces it determines who survives.
Specialty insurance was built on an assumption about how long it takes to develop underwriting judgment. Twenty years. Maybe more in complex classes of business. That development timeline was itself the competitive moat. It took decades to build the loss experience, the pattern recognition, the instinct for when clean-looking risk is actually toxic. The barrier to entry was time and scars.
AI pricing models have compressed the quantitative layer of underwriting into a commodity. Any carrier with sufficient data can run aggregation analysis, price standard risks, and generate quotes at speed. The quantitative moat is gone. What remains is the override layer: the senior underwriter who looks at a model-approved risk and says no because they remember what happened to a similar book in 2008. Or who looks at a model-rejected risk and says yes because they understand a dimension the data cannot capture.
The combined ratio is a lagging indicator. By the time it shows the damage from lost underwriting judgment, the judgment has been gone for eighteen months.
That override judgment is the real competitive asset. It is also the asset most likely to walk out the door. Three of the most experienced underwriters in many mid-market carriers are within five years of retirement. The knowledge they carry is not documented. It is not in the pricing models. It is not in any system. When they leave, the organization does not know what it lost until the loss ratios tell them. And the loss ratios take twelve to eighteen months to speak. The window to capture this judgment is not measured in strategic planning cycles. It is measured in retirement dates.
Revenue. Profit. Valuation.
Under the old model these three questions had three different answers. AI ties them together. Encode the underwriting judgment and you move all three at the same time.
Where are you losing broker placements to faster competitors?
AI-native MGAs quote in hours, not days. Brokers are consolidating and their loyalty follows speed and pricing. Every placement you lose to a faster competitor is revenue that does not come back. The broker does not call twice. The question is whether the underwriting quality that justifies a slower turnaround is visible to the broker or invisible.
What happens to the combined ratio when the override judgment retires?
The underwriters who override the model correctly are the ones keeping the combined ratio healthy. Their judgment is entirely tacit. When they retire, risk selection quality degrades invisibly. The losses emerge twelve to eighteen months later. By then, the book is already damaged. The profit question is whether the organization can sustain underwriting quality without the people who currently provide it.
Can you prove institutional underwriting discipline to reinsurers?
Reinsurance capacity and pricing terms are set by confidence in the carrier's underwriting quality. Personal expertise in a handful of heads is a risk factor. Institutional underwriting discipline encoded into systems and processes is a premium. Same book of business. Very different reinsurance economics. The carrier that can demonstrate systematic quality earns terms the one running on individual talent cannot.
Two columns. Every function in the carrier sorts itself between them.
The pattern is consistent across every function in an insurance company. Standard risk assessment, claims processing, and regulatory reporting are compressing toward commodity. The work that appreciates is the work that depends on knowing the risk, the market, and the broker at a depth an algorithm cannot match. The further a function sits from judgment, the more pressure it is under.
- Standard risk pricing and aggregation analysis
- Routine claims processing and fraud detection
- Submission intake and quote generation
- Regulatory reporting and reserving calculations
- Pipeline reporting and broker analytics
- Override judgment: knowing when the model is wrong
- Loss experience that reads risk the data misses
- Broker relationship trust and creative structuring
- Complex claims strategy and settlement judgment
- Market-turn sensing before the loss data confirms it
Whichever column the management team trains the organization into over the next three years is the company it becomes. The decision is not whether AI affects underwriting. It is which side of the line the leadership deliberately moves the organization toward.
Two paths. Same technology. Opposite outcomes.
The financial logic of the choice in front of the management team is unforgiving in either direction. The same AI technology, deployed into the same carrier, produces opposite outcomes depending on what the company chooses to defend.
| The default path | The repositioning path |
|---|---|
| Compete on speedAutomate quoting. Match AI-native turnaround. Race on price against competitors with lower cost bases. | Compete on judgment qualityMake underwriting judgment the product. Encode it into systems. Let the speed be table stakes; let the quality be the moat. |
| Let judgment stay tacitSenior underwriters carry the knowledge. Nothing is captured. Every retirement is a combined ratio risk. | Institutionalize the judgmentCapture override reasoning, loss patterns, market-turn signals. Build infrastructure that retains the judgment after the people leave. |
| Treat AI as a claims toolDeploy AI for claims and operations. Leave underwriting untouched. The function that determines profitability gets nothing. | Put AI where it matters mostAugment the underwriters. Give them tools that extend their judgment, not replace it. Build intelligence that compounds with every risk decision. |
| Hope reinsurers trust the peopleReinsurance terms rest on personal relationships. Capacity depends on individual track records that retire with the people. | Demonstrate institutional disciplineShow reinsurers a systematic underwriting edge. Earn capacity terms based on the quality of the system, not the tenure of the team. |
Same technology. Opposite outcomes. The difference is the repositioning decision, not the AI decision.
The growth levers that compound when used together
Repositioning is not a single decision. It is four levers, each available to the carrier right now, that compound when pulled together. Used in isolation, any one produces a modest gain. Used together, they rebuild the competitive position on foundations that survive a generation of retirements.
Encode override judgment before the underwriters retire
Not pricing model documentation. The reasoning. Why the senior underwriter rejected a model-approved risk. What loss pattern from 2008 informed the decision. What market signal they read that the data could not capture. Capture the override history, the rationale, and the outcome. Make the judgment institutional before the retirement dates arrive.
Turn every risk decision into compounding intelligence
Every underwriting decision, every override, every claims outcome is a signal about risk quality. Structure it, encode it, feed it back into the decision process. The carrier that captures ten years of override intelligence has an asset no AI-native MGA can replicate because they do not have the loss history. The intelligence compounds with every policy cycle.
Compress the quoting cycle without sacrificing judgment
AI-native competitors win on speed. Match the speed on standard risks by automating the quantitative layer. Protect the judgment on complex risks by augmenting the underwriter, not replacing them. The goal is not to be as fast as the algorithm on every risk. It is to be fast enough on routine risks and better on the ones that matter.
Build the reinsurance story around institutional quality
Reinsurers and capital providers price confidence. A carrier that can demonstrate systematic underwriting discipline, tracked override accuracy, and institutional loss-pattern intelligence earns meaningfully better capacity terms. The reinsurance economics shift when the underwriting story moves from "we have good people" to "we have a system that produces good underwriting."
Business first. Technology second.
GRAIL is an AI-native management consultancy. We help European mid-market leadership teams figure out the one or two things that fundamentally change about their business as AI enters their industry, and then build the capability to act on it before competitors do. For insurance specifically, the challenge is not technical. AI pricing tools are abundant. The challenge is strategic: how to encode and extend the human judgment that actually determines combined ratio performance, before the people who carry it retire.
The market offers two things: vendor lock-in dressed as transformation, and consulting reports dressed as strategy. GRAIL delivers a third option: working AI capability that you own.
- Senior advisory direct to the CEO and GMT
- Working AI capability you own from day one
- Custom agents built around your business logic
- Outcomes in weeks, not quarters
- No lock-in at any phase of the engagement
- Founded by operators, not technologists
- Business-first strategy, technology second
- Context architecture, change management, workflow design
- Results before you commit to scale
- Each next step earned, never assumed
Three sessions with your management team. No IT involvement. Working tools from week one.
GRAIL starts with the management team because organizational transformation cannot outrun the leadership team's personal understanding of what is possible. Three workshops. Each delivers standalone value. Each earns the right to the next.
How to think
The strategic foundation. Where AI creates real value in insurance and where it is noise. The augmentation framework. The underwriting judgment thesis. Your leadership team leaves with a shared frame for the rest of the work, and with the first working agent built live in the room.
Your AI team
A half-day activation. Each member of the management team receives a personal suite of five to ten custom agents trained on their workflow, their decisions, their competitive landscape. Risk assessment augmentation. Override tracking. Broker intelligence. Working tools from week one, not slides about tools.
Competitive edge
Refinement from real usage. Agents upgraded based on how the team actually used them. The judgment encoding roadmap. The reinsurance positioning assessment. The recommendation for what comes next, earned by what just shipped.
Three weeks. No IT involvement. No board approval needed to start. The sharpest strategic conversation your leadership team will have this year, backed by working tools they are already using.
What to ask in your next leadership meeting
The questions where the management team cannot agree on an answer are the ones worth a longer conversation. Ask these honestly. The point is not the polished response. The point is whether the answer would survive contact with a major reinsurer three months from now.
How many of your underwriting overrides in the last year improved the outcome versus the model's recommendation, and does anyone track that systematically?
If your three most experienced underwriters retired this year, what happens to the combined ratio in eighteen months, and can you quantify it?
When an AI-native MGA wins a placement from one of your key brokers, what is your competitive response, and does the leadership team agree on it?
What fraction of your underwriting judgment is institutional versus personal, and could a new hire reconstruct it from what is in your systems today?
When your reinsurers ask why your underwriting quality will hold after the next round of retirements, is the answer a name or a system?
If any of these questions land somewhere uncomfortable, that is the conversation worth having.
Continue reading
Sources and limitations
This briefing draws on GRAIL's engagement experience with leadership teams and on public company disclosures. Figures are illustrative unless a source is named beside them. A sourced edition is in preparation.